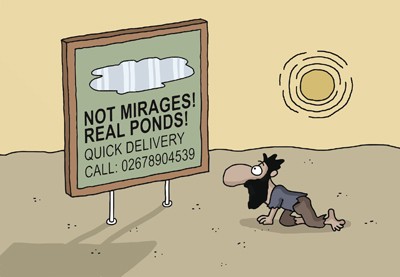
A savings mirage?
Among the pitfalls of saving and investing for retirement is to mislead ourselves about the true state of our finances.
An almost textbook example can involve the self-employed. Most of us must have heard small business owners from time to time say things like: "My business is my super". Their intention is, of course, to eventually sell their businesses to finance their retirement – possibly putting the proceeds into super.
As Smart Investing discussed recently (A paradoxical relationship: The self-employed and super), updated research by the Association of Superannuation Funds of Australia (ASFA) confirms once again that the majority of self-employed have little or no super.
This can lead to the issue about how much the self-employed can rely on the value of their businesses as a source of retirement finance to supplement any super and the Age pension.
The authors of the research paper, ASFA's director of research Ross Clare and senior research adviser Andrew Craston, note that ABS figures for 2013-14 suggest that the self-employed, on average, accumulate more non-housing wealth than employees. These non-housing, non-super assets typically comprise cash, shares and business assets.
Indeed, business assets can be a "substantial contributor" to the average wealth of the self-employed.
But as Clare and Craston write, "average figures do not tell the whole story".
The non-housing, non-super assets (including business assets) of the self-employed are likely to vary significantly between individuals.
"For some self-employed individuals," Clare and Craston add, "the value of the business might be little more than the market value of a second-hand utility or truck and some tools of trade. For others, it might be the value of an ongoing business worth a million dollars or more."
(Of course, once businesses become really valuable, many owners would decide to change their business structure, moving away from being self-employed owner-managers of non-incorporated businesses.)
Another way that ASFA has attempted to measure the value of small business assets when owners retire is to look at the capital gains tax (CGT) concessions gained by eligible small business owners upon their possible retirement and sale of their enterprises. This makes interesting reading.
According to tax office statistics for 2012-13, 4,545 vendors of small businesses gained CGT retirement exemptions totalling a little more than $618 million in value. A further 870 small business vendors gained CGT small business, 15-year exemptions (for businesses owned for that length of time) totalling $397.2 million in value. These statistics should be put into context.
Retiring vendors of valuable small businesses would obviously want to benefit from any CGT concessions available from the sale of business assets. Yet considering the huge number of small businesses in Australia, it seems that the value of proceeds from the sale of business assets being used to help finance retirement is modest. And calculating the average concessions again can give a misleading impression.
Self-employed business owners obviously make up just one part of society that may be vulnerable to over-estimating the value of their assets as a means to help provide retirement capital.
Another example are homeowners who may be intending to downgrade or downsize their family homes to provide extra retirement money without first doing the necessary number-crunching.
Whether we are talking about the self-employed, homeowners who are intending to downgrade or whoever, it is important to consider gaining professional quality advice and to make informed decisions about the real adequacy of our retirement savings.
We should be confident that our perceived retirement savings are not a mirage of our own making.
By Robin Bowerman
Smart Investing
Principal & Head of Retail, Vanguard Investments Australia
21 August 2016
Latest eNewsletters
Hot Issues
- Five steps towards a more confident retirement
- Financial literacy in Australia: Where we're improving (and falling behind)
- CSLR levy on SMSFs unfair
- SMSF pension shortfall – when can trustees self-assess?
- How to turn your annual SMSF investment strategy review into a genuine analytical exercise
- Super viewed as mortgage solution
- Tokenisation to change SMSF landscape
- Check out the largest castles by country
- ATO’s LRBA data significantly less than industry figures
- New deeming thresholds could deliver small part age pension
- Can I still get the Age Pension if my super is healthy?
- New to SMSFs? Start preparing for your first SAR lodgment
- Contribution splitting now more valuable
- Six ways Gen X can build retirement savings
- How to maximise the impact of your inheritance
- How Our Diets have Changed.
- Adequate retirement savings misjudged
- The SBSCH will close from 1 July 2026
- Complications of maintaining two cost bases in Div 296
- What the Payday Super changes mean for your retirement
- investment and economic outlook 2026
- Rules apply to gifting in superannuation
- Record SMSF growth driven by digital access
- The evolution of the world's languages
- Minimum pension drawdown not the only thing to consider as 30 June approaches
- ASIC urges Aussies to check for unclaimed money
- PAYDAY SUPER STARTS 1 JULY 2026 – Planning guides
Article archive
- April - June 2026
- January - March 2026
- October - December 2025
- July - September 2025
- April - June 2025
- January - March 2025
- October - December 2024
- July - September 2024
- April - June 2024
- January - March 2024
- October - December 2023
- July - September 2023
- April - June 2023
- January - March 2023
- October - December 2022